Your salary may look great on your job offer, but your paycheck can feel much smaller when payday arrives. If you work in New York City, several taxes and payroll deductions can reduce the amount of money you actually receive.
The good news is that understanding your paycheck does not have to be complicated. Once you know which deductions apply to you, you can estimate your take-home pay, review your pay stub, and plan your monthly budget more confidently.
In this guide, we explain why NYC paychecks can be lower than expected, which taxes are deducted, and what you can do to understand your earnings in 2026.
Why Is My Paycheck So Much Lower Than My Salary?
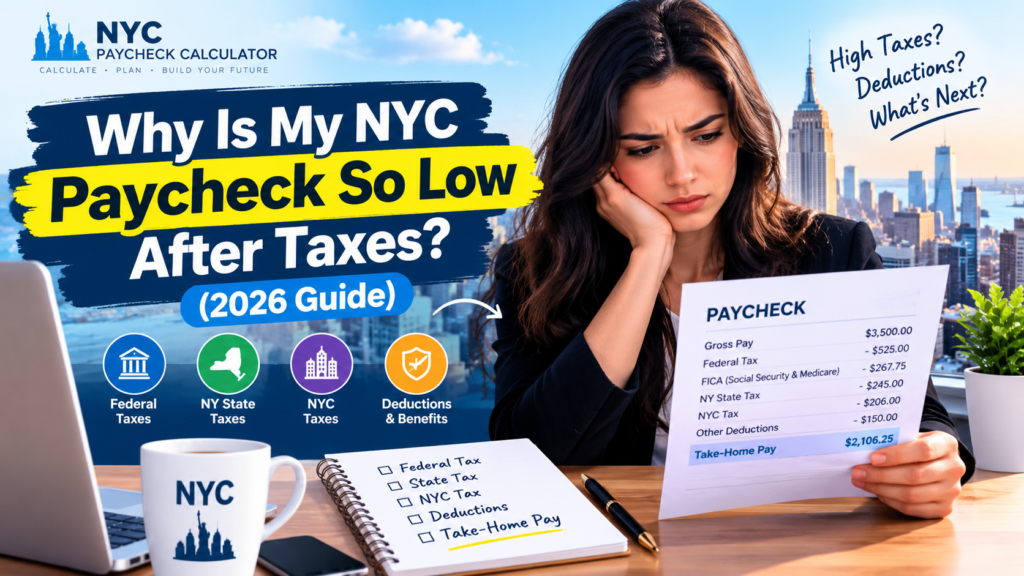
Your annual salary is usually your gross pay, not the amount deposited into your bank account. Your employer may withhold federal income tax, New York State income tax, New York City income tax, Social Security, and Medicare.
You may also have deductions for health insurance, retirement contributions, or other employee benefits.
For example, someone earning $85,000 annually does not generally receive $85,000 in take-home pay. Their actual net income depends on their filing status, tax withholding elections, benefits, and other circumstances.
The amount left after taxes and deductions is called net pay or take-home pay.
1. Federal Income Tax
Federal income tax is one of the main deductions from an employee’s paycheck. The amount withheld depends on factors such as your earnings, filing status, and Form W-4.
The United States uses a progressive federal income tax system. This means different portions of your taxable income are taxed at different rates. Moving into a higher tax bracket does not mean all your income is taxed at that higher rate.
For 2026, the federal income tax brackets for single filers include rates of 10%, 12%, 22%, 24%, 32%, 35%, and 37%, depending on taxable income.
Your federal withholding may not exactly match your final tax liability. The difference is settled when you file your federal tax return.
Official reference: IRS — 2026 Tax Rate Schedules
2. New York State Income Tax
New York State income tax is another reason your paycheck may be smaller than expected.
The amount depends on your taxable income, filing status, applicable deductions, and state withholding elections. New York’s tax brackets and rules are separate from federal tax rules.
For 2026, New York updated its state income tax withholding tables to reflect changes in the tax rates. Therefore, it is important to use current-year figures when estimating your paycheck.
You can review the official withholding guidance here:
New York State — 2026 Withholding Tax Information
3. New York City Income Tax
If you live in New York City, you may also owe NYC personal income tax.
This is separate from federal income tax and New York State income tax. NYC residents can therefore have several income tax obligations affecting the same earnings.
Your actual city tax depends on your taxable income and filing status. The amount withheld from your paycheck may also differ from your final annual liability.
It is important to distinguish between living in NYC and working in NYC. Your residence, work location, and individual tax circumstances can affect which local tax rules apply.
4. Social Security and Medicare Taxes
Social Security and Medicare taxes are commonly grouped together as FICA taxes.
For most employees in 2026:
- Social Security: 6.2% of applicable wages, up to the annual wage limit of $184,500.
- Medicare: 1.45% of applicable wages, with no general annual wage cap.
- Additional Medicare Tax: An extra 0.9% may apply to Medicare wages above the applicable threshold.
For a typical employee earning less than the Social Security wage limit, the combined employee share of Social Security and Medicare is 7.65% of applicable wages.
These payroll taxes are separate from federal, state, and city income taxes, which is why they can make a noticeable difference to take-home pay.
Official reference: IRS — Social Security and Medicare Withholding Rates
5. Health Insurance and Retirement Contributions
Not every paycheck deduction is a tax.
Your employer may deduct money for:
- Health, dental, or vision insurance
- Traditional 401(k) retirement contributions
- Health Savings Account contributions
- Flexible Spending Account contributions
- Other employee benefits or authorized deductions
For example, if you contribute part of your salary to a retirement plan, the amount deposited into your bank account may decrease. However, eligible traditional 401(k) contributions generally reduce federal income-taxable wages while remaining subject to Social Security and Medicare taxes.
The treatment of benefits varies, so review the deduction labels on your pay stub rather than assuming every deduction is a tax.
Example: What Happens to an $85,000 NYC Salary?
Suppose you earn $85,000 per year and receive a regular paycheck from an employer.
Your annual gross salary is $85,000, but that does not mean you receive $85,000 in your bank account.
What Is on Your NYC Paycheck?
| Paycheck item | What it means |
|---|---|
| Gross pay | Your earnings before deductions |
| Federal income tax | Federal income tax withheld |
| NY State income tax | State income tax withheld |
| NYC income tax | Local income tax, if applicable |
| Social Security | Employee payroll tax |
| Medicare | Employee payroll tax |
| Benefits | Insurance and other elected deductions |
| Net pay | The amount remaining after deductions |
The exact take-home amount cannot be determined from salary alone. Filing status, tax elections, eligible deductions, benefits, and pay frequency can all affect the result.
For a more useful estimate, enter your own details into a paycheck calculator instead of relying on a generic percentage.
- Federal tax
- NY State tax
- NYC tax
- Social Security & Medicare
Replace the example URL with the actual URL of your calculator before publishing.
Why Does My Paycheck Change From One Pay Period to Another?
If your paycheck changes from week to week or month to month, there may be a straightforward explanation.
Common reasons include:
Different working hours: Hourly employees may earn different amounts each pay period.
Overtime or bonuses: Additional compensation can change gross pay and withholding.
Changes to benefits: Starting insurance coverage or adjusting retirement contributions can change deductions.
Tax withholding elections: Changes to your Form W-4 or applicable state withholding certificate can affect the amount withheld.
Supplemental wages: Bonuses and other supplemental payments may be subject to different withholding methods.
Annual limits: Certain payroll taxes, such as Social Security, have annual wage limits that can affect withholding once those limits are reached.
If the change seems unusual, compare your current pay stub with a previous one. Look at gross earnings, taxable wages, each deduction, and net pay.
How Can I Check Whether My NYC Paycheck Is Correct?
Use these steps to review your paycheck:
- Check your gross earnings. Confirm your salary, hours, overtime, and any bonuses.
- Review federal withholding. Compare the amount with your current Form W-4 and payroll information.
- Check state and city withholding. Make sure your filing information and residence details are correct.
- Review FICA taxes. Check Social Security and Medicare deductions against applicable wages and rates.
- Inspect benefit deductions. Verify your insurance premiums and retirement contributions.
- Compare net pay. Check whether the final deposit matches the amount shown on your pay stub.
If you still see an unexpected deduction, ask your payroll department for an explanation. If necessary, consult a qualified tax professional.
Can I Increase My Take-Home Pay?
You may be able to improve your take-home pay by reviewing your payroll elections and benefits, but the right approach depends on your circumstances.
Consider reviewing your Form W-4 and New York withholding certificate if your withholding appears too high or too low. You can also check whether employer benefits and eligible retirement contributions fit your financial goals.
Be careful not to reduce withholding simply to increase your current paycheck. Withholding too little can leave you with a tax bill or potential penalties when you file.
The goal is to make sure your withholding is appropriate—not merely to make every paycheck as large as possible.
Frequently Asked Questions
Why is my NYC paycheck so low after taxes?
Your paycheck may include federal income tax, New York State income tax, NYC income tax, Social Security, Medicare, and employee benefit deductions. The combined effect can make your take-home pay substantially lower than your gross salary.
How much tax is taken out of a paycheck in NYC?
There is no single percentage that applies to everyone. Your effective tax burden depends on income, filing status, applicable deductions, payroll taxes, and other personal circumstances.
Does NYC have its own income tax?
Yes. NYC residents may owe New York City personal income tax in addition to federal and New York State income taxes.
Is net pay the same as take-home pay?
Yes. Net pay generally refers to the amount remaining after payroll taxes and other applicable deductions. It is the amount paid to you, usually through direct deposit or a paycheck.
Why is my bonus taxed more than my regular paycheck?
Bonuses may use supplemental-wage withholding methods. The withholding on a bonus does not necessarily represent your final tax rate on that money. Your final liability is determined under the applicable tax rules when you file your return.
How can I estimate my NYC take-home pay for 2026?
Use a calculator that accounts for your salary, pay frequency, filing status, federal tax, New York State tax, NYC tax where applicable, and FICA taxes. Include relevant deductions for a more personalized estimate.
Final Thoughts
A lower-than-expected paycheck does not automatically mean your employer has made a mistake. Federal, state, and local taxes, payroll taxes, and employee benefits can all affect your take-home pay.
The best way to understand the difference is to review each deduction individually and compare your gross earnings with your net pay.
Use a current-year NYC paycheck calculator to estimate what you may take home in 2026, then compare the estimate with your actual pay stub. Remember that calculator results are estimates, and your final tax liability may differ.
Disclaimer: This article provides general educational information and is not tax or legal advice. Tax rates, withholding, and individual circumstances may change the final result.
1 thought on “Why Is My NYC Paycheck So Low After Taxes? (2026 Guide)”