Last updated: November 13, 2026 | Tax year 2026 (2027 preview included) | Single filer, W-2 employee
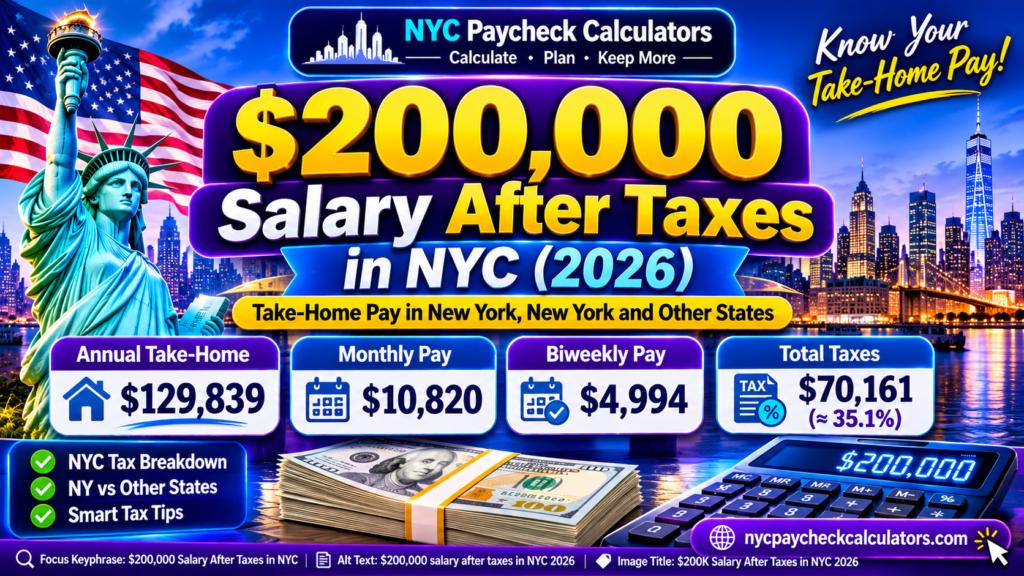
Quick answer: If you earn $200,000 a year and live in New York City, you take home about $129,839 per year, which is roughly $10,820 per month or $4,994 every two weeks, after federal income tax, Social Security, Medicare, New York State tax, NYC tax and New York payroll deductions. That is a total tax load of about 35.1%.
Where you live changes the answer a lot. Here is the short version:
| Where you live | Total taxes | Annual take-home | Monthly | Biweekly | Weekly |
|---|---|---|---|---|---|
| New York City | $70,161 | $129,839 | $10,820 | $4,994 | $2,497 |
| New York State (outside NYC) | $62,844 | $137,156 | $11,430 | $5,275 | $2,638 |
| State with no income tax (TX, FL, etc.) | $51,073 | $148,927 | $12,411 | $5,727 | $2,864 |
The rest of this guide shows exactly how each number is calculated, so you can check it line by line, then shows how to legally keep more of your paycheck.
What this calculation assumes
All figures use official 2026 tax rules and these assumptions:
- Filing status: single, no dependents, no tax credits
- Income: $200,000 in W-2 wages only
- Deductions: standard deduction (federal $16,100, New York $8,000)
- No 401(k), HSA, health insurance or commuter deductions (we add those in a later section)
- NYC figures assume you live in New York City (NYC income tax applies to residents)
Your real paycheck can differ because of your W-4, benefits, bonuses and any credits. Use this as a planning number, not a payroll guarantee.
Step 1: Federal income tax on $200,000 (2026)
Federal tax is calculated on taxable income, not your gross salary. For 2026 the standard deduction for a single filer is $16,100.
$200,000 minus $16,100 = $183,900 taxable income
Then each slice of income is taxed at its own rate (this is why you never pay 24% on the whole amount):
| 2026 bracket (single) | Income taxed in this bracket | Tax |
|---|---|---|
| 10% up to $12,400 | $12,400 | $1,240 |
| 12% from $12,400 to $50,400 | $38,000 | $4,560 |
| 22% from $50,400 to $105,700 | $55,300 | $12,166 |
| 24% from $105,700 to $201,775 | $78,200 | $18,768 |
| Total federal income tax | $36,734 |
Your marginal federal rate is 24%, but your effective federal rate is only about 18.37% of your gross salary.
Step 2: Social Security and Medicare (FICA)
| Payroll tax | Rate | On your $200,000 | Amount |
|---|---|---|---|
| Social Security | 6.2% up to the $184,500 wage base | $184,500 | $11,439 |
| Medicare | 1.45% on all wages | $200,000 | $2,900 |
| Additional Medicare | 0.9% on wages over $200,000 | $0 | $0 |
| Total FICA | $14,339 |
Two important details for a $200K earner:
- Social Security stops at $184,500. The 2026 wage base is $184,500, so the maximum Social Security tax is $11,439. Once you pass that amount, Social Security tax stops coming out of your paycheck for the rest of the year.
- The 0.9% Additional Medicare Tax starts above $200,000. Employers must withhold it on wages over $200,000, regardless of filing status. At exactly $200,000 you pay none of it, but every extra dollar (a raise or a bonus) is taxed at 2.35% Medicare instead of 1.45%.
Step 3: New York State income tax
New York taxes you on your income minus its own $8,000 standard deduction (not the federal $16,100):
$200,000 minus $8,000 = $192,000 New York taxable income
For 2026, New York’s five lowest rates were cut by 0.1 percentage point. The 2026 single-filer rates start at 3.9% and move up through 4.4%, 5.15%, 5.4% and 5.9% before reaching 6.85% above $215,400.
If you simply applied each bracket, the tax would be about $10,760. But high earners hit New York’s tax benefit recapture. Once your New York adjusted gross income passes $157,650, the benefit of the lower brackets is fully taken back and your whole taxable income is taxed at the 5.9% rate (while your taxable income stays under $215,400):
$192,000 x 5.9% = $11,328 New York State tax
That recapture is the reason many online calculators show a lower, incorrect number for $200K salaries in New York.
Step 4: New York City income tax (residents only)
NYC residents pay a separate city income tax on the same $192,000 of taxable income. The 2026 NYC rate schedule for a single filer:
| NYC taxable income | Rate | Tax |
|---|---|---|
| First $12,000 | 3.078% | $369.36 |
| $12,000 to $25,000 | 3.762% | $489.06 |
| $25,000 to $50,000 | 3.819% | $954.75 |
| Over $50,000 ($142,000 here) | 3.876% | $5,503.92 |
| Total NYC tax | $7,317 |
If you live in Westchester, Long Island, New Jersey or anywhere else outside the five boroughs, you do not pay this. That alone is worth about $7,317 a year at this salary.
Step 5: New York Paid Family Leave and disability
New York also deducts two small payroll items from your pay after tax:
- Paid Family Leave (PFL): 0.432% of gross wages in 2026, capped at $411.91 per year. At $200,000 you hit the cap.
- Disability (DBL): 0.5% of wages up to a maximum of $0.60 per week, which is $31.20 per year.
Total: $443.11 per year.
The full $200,000 breakdown for a NYC resident
| Item | Annual amount | % of gross |
|---|---|---|
| Gross salary | $200,000 | 100% |
| Federal income tax | $36,734 | 18.37% |
| Social Security and Medicare | $14,339 | 7.17% |
| New York State income tax | $11,328 | 5.66% |
| New York City income tax | $7,317 | 3.66% |
| NY Paid Family Leave and disability | $443 | 0.22% |
| Total taxes and deductions | $70,161 | 35.08% |
| Take-home pay | $129,839 | 64.92% |
Your approximate marginal rate on the next dollar earned in NYC is about 35% (24% federal + 5.9% New York + 3.876% NYC + 1.45% Medicare).
$200,000 salary: hourly, weekly, biweekly and monthly (NYC)
| Pay period | Gross | Take-home (NYC) |
|---|---|---|
| Yearly | $200,000 | $129,839 |
| Monthly | $16,667 | $10,820 |
| Semi-monthly (24 checks) | $8,333 | $5,410 |
| Biweekly (26 checks) | $7,692 | $4,994 |
| Weekly | $3,846 | $2,497 |
| Hourly (2,080 hours) | $96.15 | $62.42 |
Your paychecks get bigger at the end of the year
Because Social Security tax stops once you reach $184,500 of wages, your last paychecks of the year are larger. On a biweekly schedule the 24th check is partly exempt and the final two checks have no Social Security withholding at all, which adds roughly $477 to each of those checks.
NYC vs. New York State vs. a no-income-tax state
| NYC | NY State (outside NYC) | No state income tax | |
|---|---|---|---|
| Federal income tax | $36,734 | $36,734 | $36,734 |
| FICA | $14,339 | $14,339 | $14,339 |
| State income tax | $11,328 | $11,328 | $0 |
| City income tax | $7,317 | $0 | $0 |
| NY PFL and disability | $443 | $443 | $0 |
| Take-home pay | $129,839 | $137,156 | $148,927 |
Compared with a state like Texas or Florida, living in NYC costs you about $19,088 per year in extra taxes, or roughly $1,591 per month. Of course, housing, commuting and salary levels differ too, so compare the full picture before moving. Some states without income tax still have small payroll deductions of their own.
How to keep more of a $200,000 salary (legally)
1. Max out your 401(k)
The 2026 employee limit is $24,500. Traditional 401(k) contributions reduce your federal, New York and NYC taxable income (but not Social Security and Medicare tax).
| NYC resident | No 401(k) | Max $24,500 traditional 401(k) |
|---|---|---|
| Federal income tax | $36,734 | $30,854 |
| New York State tax | $11,328 | $9,883 |
| NYC tax | $7,317 | $6,367 |
| FICA | $14,339 | $14,339 |
| NY PFL and disability | $443 | $443 |
| Total taxes | $70,161 | $61,886 |
| Cash take-home | $129,839 | $113,614 |
You put $24,500 into retirement, but your take-home pay only drops by about $16,225, because you save roughly $8,275 in taxes. In other words, each dollar you save costs you about 66 cents of paycheck.
If you are 50 or older, you can add an extra $8,000 catch-up contribution in 2026 ($11,250 if you are 60 to 63). Starting in 2026, employees whose prior-year FICA wages were above $150,000 must make catch-up contributions as Roth (after-tax).
2. Use an HSA or FSA
For 2026 the HSA limit is $4,400 for self-only coverage ($8,750 family), and the health FSA limit is $3,400. Contributions through payroll also avoid FICA tax.
3. Use pre-tax commuter benefits
NYC workers can set aside pre-tax money for transit. The 2026 monthly limit is $340.
4. Check whether itemizing beats the standard deduction
At $200,000 in NYC you pay about $18,645 in state and city income tax ($11,328 + $7,317). That alone is more than the $16,100 standard deduction. The federal cap on state and local tax (SALT) deductions is $40,400 for 2026, so itemizing can lower your federal bill, especially if you also pay mortgage interest, property tax or make charitable gifts. With state and city income tax only, the extra deduction is about $2,545, which saves roughly $611 at the 24% rate.
5. Choose Traditional or Roth on purpose
Traditional contributions save tax now. Roth contributions give tax-free withdrawals later. At a 24% federal bracket plus about 9.8% New York and NYC tax, many high earners prefer Traditional now, but the right answer depends on your expected retirement tax rate.
Married filing jointly (one earner at $200,000)
If you are married and file jointly and all $200,000 is one spouse’s salary, the 2026 standard deduction is $32,200, taxable income is $167,800, and federal income tax is about $26,340, about $10,394 lower than the single-filer result. FICA stays at $14,339. State and city tax also change under joint rules, so use a calculator for the exact NYC figure.
Is $200,000 a good salary in New York City?
Take-home of about $10,820 per month supports a comfortable lifestyle in NYC, but it is not unlimited. A simple 50/30/20 split of your monthly take-home looks like this:
| Bucket | Share | Monthly amount |
|---|---|---|
| Needs (rent, utilities, transit, insurance, groceries) | 50% | $5,410 |
| Wants (dining, travel, shopping) | 30% | $3,246 |
| Savings and investing | 20% | $2,164 |
If you already max out a 401(k) you are saving more than 20%, so you may want to shift the rest of the budget accordingly.
2027 preview: how your $200,000 paycheck changes next year
Federal income tax on $200,000 falls by about $359 in 2027, but Social Security tax rises by about $484, so your take-home after federal and payroll taxes is about $125 lower. The IRS announced the 2027 numbers on November 5, 2026 (Rev. Proc. 2026-35) and the SSA announced the new wage base on October 14, 2026.
| Item (single filer, $200,000 salary) | 2026 | 2027 |
|---|---|---|
| Standard deduction | $16,100 | $16,600 |
| Taxable income | $183,900 | $183,400 |
| 24% bracket starts at | $105,700 | $109,125 |
| Federal income tax | $36,734 | $36,375 |
| Social Security wage base | $184,500 | $192,300 |
| Social Security tax | $11,439 | $11,923 |
| Medicare tax (1.45%) | $2,900 | $2,900 |
| Additional Medicare tax | $0 | $0 |
| Federal tax plus FICA | $51,073 | $51,198 |
| Take-home before state and city tax | $148,927 | $148,802 |
| 401(k) employee limit | $24,500 | $25,500 |
| 401(k) catch-up (age 50+) | $8,000 | $8,500 |
This preview covers federal and payroll taxes only. The NYC figures in this guide use 2026 New York State and NYC rules, and we will add the 2027 state and city amounts once they are finalized.
Frequently Asked Questions
Frequently Asked Questions
How much is $200,000 a year after taxes in NYC?Click this!
About $129,839 per year for a single filer using the standard deduction in 2026. That is about $10,820 per month and $4,994 per biweekly paycheck.
How much is $200,000 a year after taxes in New York State, outside NYC?Click this!
About $137,156 per year, or $11,430 per month, because you skip the $7,317 NYC income tax.
How much is $200,000 a year after taxes with no state income tax?Click this!
About $148,927 per year, or $12,411 per month, before any small state payroll deductions.
What is $200,000 a year per hour?Click this!
About $96.15 per hour before tax, based on 2,080 working hours per year. After tax in NYC it is about $62.42 per hour.
What federal tax bracket is $200,000 in for 2026?Click this!
A single filer with $200,000 of wages has $183,900 of taxable income, which falls in the 24% bracket (the 24% bracket runs from $105,700 to $201,775 of taxable income).
Do I pay the 0.9% Additional Medicare Tax at $200,000?Click this!
Not on exactly $200,000. The extra 0.9% applies only to Medicare wages above $200,000. If your total pay is $215,000, for example, the extra 0.9% applies to the extra $15,000.
Does Social Security tax stop at some point?Click this!
Yes. In 2026 you pay 6.2% Social Security tax only on the first $184,500 of wages, a maximum of $11,439.
Is the NYC income tax the same for everyone in the city?Click this!
NYC tax applies only to people who live in the city, and the rate rises from 3.078% to 3.876% across four brackets. Most $200K earners pay the top 3.876% on most of their income.
Will my real paycheck match these numbers exactly?Click this!
Not always. Your W-4 and NY IT-2104 elections, pre-tax benefits (health insurance, 401(k), HSA, commuter), bonuses and credits all change the final figure. Use these numbers to plan, then confirm with your pay stub or a tax professional.
Do the 2027 tax numbers change this?Click this!
Slightly. For 2027 the IRS raised the single standard deduction to $16,600 and the Social Security wage base rises to $192,300. Together they leave your federal and payroll take-home about $125 lower at a $200,000 salary, before New York State and NYC tax. See the 2027 preview above.
Calculate your own NYC take-home pay
Every situation is a little different (bonus, 401(k), dependents, filing status). Use the NYC Paycheck Calculator on this site to enter your exact salary and get your own federal, New York State, NYC and FICA breakdown in seconds.
This article is for general information only and is not tax, legal or financial advice. Tax laws change, so confirm important decisions with a qualified tax professional.