Ever looked at your salary and wondered, “Where did all that money go?”
Your annual salary is not the same as the amount that reaches your bank account. A New York paycheck can include federal income tax, Social Security, Medicare, New York State income tax, and, for NYC residents, New York City income tax. Benefits, retirement contributions, and other payroll deductions can reduce your take-home pay even further.
The good news is that you do not need to be a tax expert to understand how your paycheck works.
This guide explains how New York paycheck deductions work in 2026, what each deduction means, and how you can estimate your take-home pay from gross wages.
Important: Payroll withholding is an estimate based on your income, withholding forms, pay frequency, deductions, and applicable tax rules. Your paycheck withholding is not necessarily the same as your final tax liability when you file your tax return.
How Do You Calculate a New York Paycheck?
A simple way to think about your paycheck is:
Gross Pay − Applicable Deductions and Withholding = Net Pay
Depending on your situation, those deductions may include:
- Federal income tax
- Social Security
- Medicare
- New York State income tax
- New York City income tax
- Yonkers tax, when applicable
- Paid Family Leave
- Retirement contributions
- Health insurance
- Other payroll deductions
Not every employee has every deduction.
For example, a New York City resident can have both New York State and NYC personal income tax withheld, while someone who lives outside NYC generally does not pay NYC resident income tax simply because they work in the city.
Step 1: Start With Your Gross Pay
Gross pay is the amount you earn before taxes and other payroll deductions.
For a salaried employee, you can estimate gross pay per paycheck by dividing your annual salary by the number of pay periods.
| Pay Schedule | Approx. Paychecks Per Year |
|---|---|
| Weekly | 52 |
| Biweekly | 26 |
| Semimonthly | 24 |
| Monthly | 12 |
Example: $80,000 Annual Salary
If you earn $80,000 per year and receive 26 biweekly paychecks:
$80,000 ÷ 26 = $3,076.92 gross pay per paycheck
That $3,076.92 is your gross paycheck, not your take-home pay.
If you are paid hourly, your starting calculation is usually:
Hourly Rate × Hours Worked = Gross Pay
Overtime, bonuses, commissions, and other taxable compensation can increase your gross wages.
Step 2: Look at Your Pre-Tax Deductions
Some payroll deductions can be taken before certain taxes are calculated.
Depending on the specific plan and tax rules, examples may include:
- Traditional 401(k) contributions
- Certain employer-sponsored health insurance premiums
- HSA contributions made through an eligible payroll arrangement
- FSA contributions
- Certain commuter benefits
But there is an important detail:
A pre-tax deduction does not necessarily reduce every type of tax.
For example, traditional 401(k) contributions generally reduce federal income-taxable wages, but they generally remain subject to Social Security and Medicare taxes.
That’s why you should not simply subtract every deduction from your salary and then apply one tax percentage.
Step 3: Calculate Federal Income Tax
Federal income tax is usually one of the biggest deductions from an employee’s paycheck.
Employers generally use information from your Form W-4, your wages, pay frequency, and IRS withholding procedures to determine federal income-tax withholding.
For tax year 2026, the federal marginal tax rates are:
- 10%
- 12%
- 22%
- 24%
- 32%
- 35%
- 37%
The 2026 federal standard deduction is:
| Filing Status | 2026 Standard Deduction |
|---|---|
| Single | $16,100 |
| Married Filing Jointly | $32,200 |
| Head of Household | $24,150 |
These figures are important when understanding federal taxable income, but you should not simply multiply your entire salary by your tax bracket.
The U.S. federal income tax system is progressive. Different portions of taxable income can be taxed at different rates.
Step 4: Calculate Social Security Tax
Social Security is one part of FICA, the Federal Insurance Contributions Act taxes.
For 2026:
Employee Social Security rate: 6.2%
The 2026 Social Security wage base is:
$184,500
This means Social Security tax generally applies to covered wages up to $184,500 for the year. Once an employee reaches that wage base, Social Security withholding stops for the remainder of that calendar year.
Simple Example
If a paycheck contains $3,000 of wages subject to Social Security tax:
$3,000 × 6.2% = $186
So the Social Security portion would be approximately $186 for that paycheck.
The actual payroll calculation can depend on the employee’s wage and payroll circumstances.
Step 5: Calculate Medicare Tax
Medicare is the other major component of FICA.
For 2026, the employee Medicare tax rate is:
1.45%
Unlike Social Security, Medicare has no wage base limit.
Simple Example
If $3,000 of wages are subject to the regular Medicare tax:
$3,000 × 1.45% = $43.50
So approximately $43.50 would represent the regular Medicare portion.
The IRS confirms that the 2026 Medicare rate is 1.45% for employees and there is no Medicare wage-base limit.
What Is the Additional Medicare Tax?
Higher earners can also be subject to an additional 0.9% Medicare tax.
Employers generally begin withholding this additional amount from an employee’s wages once wages paid by that employer exceed $200,000 during the calendar year.
The $200,000 threshold is an employer withholding threshold. Your final Additional Medicare Tax liability when you file your return can depend on your filing status and total wages.
Step 6: Calculate New York State Income Tax
New York has its own state personal income tax in addition to federal income tax.
This is where many paycheck calculations become confusing.
You should not simply take your annual salary and multiply it by one New York tax rate.
New York uses progressive tax rates and official withholding methods.
For 2026, New York updated its withholding tables and methods following changes to the state’s personal income tax rate schedules. Employers use the applicable NYS-50-T-NYS (1/26) tables and methods for payroll made on or after January 1, 2026.
Your New York withholding can depend on factors such as:
- Filing status
- Wages
- Pay frequency
- Form IT-2104 information
- Withholding allowances or adjustments
- Additional withholding
- Other payroll information
This is why two employees with the same salary can have different New York withholding.
Step 7: Do You Pay New York City Income Tax?
If you are a New York City resident, NYC personal income tax can apply in addition to New York State income tax.
For 2026, the NYC resident tax rates are:
- 3.078%
- 3.762%
- 3.819%
- 3.876%
The applicable rate depends on taxable income and filing status. New York City has separate withholding tables and methods for 2026.
Important NYC Tax Difference
Living in NYC and working in NYC are not the same thing for this tax.
If you live in New York City, NYC resident income tax can apply.
If you work in NYC but live outside the city, simply working in NYC does not automatically make you an NYC resident for personal income-tax purposes.
Your residency circumstances can matter, so do not determine NYC tax solely from your work address.
Step 8: What About Yonkers?
Yonkers has separate withholding rules.
New York State publishes specific withholding tables for:
- New York State
- New York City
- Yonkers
For 2026, the state provides a separate NYS-50-T-Y (1/26) publication for Yonkers resident and nonresident withholding.
So your location can make a meaningful difference when estimating your New York paycheck.
Step 9: Understand Paid Family Leave
New York Paid Family Leave can also appear as a payroll deduction for covered employees.
For 2026, the employee contribution is:
0.432% of gross wages per pay period
The maximum annual employee contribution is:
$411.91
The contribution applies to covered employees under the state’s Paid Family Leave program.
This deduction is easy to overlook when comparing your salary with the amount that actually reaches your bank account.
Step 10: Add Other Payroll Deductions
Taxes aren’t the only reason your paycheck may be smaller than your salary.
Your paycheck can also include deductions for:
Retirement
- Traditional 401(k)
- Roth 401(k)
- 403(b)
- Other employer retirement plans
Insurance
- Health insurance
- Dental insurance
- Vision insurance
- Other employee-paid insurance
Spending Accounts
- HSA
- FSA
- Dependent-care FSA
Other Payroll Deductions
Depending on your situation, your paycheck can also contain:
- Union dues
- Wage garnishments
- Certain voluntary deductions
- Other employer-authorized deductions
The tax treatment of these deductions can be different, so you should not assume they all reduce taxable wages in the same way.
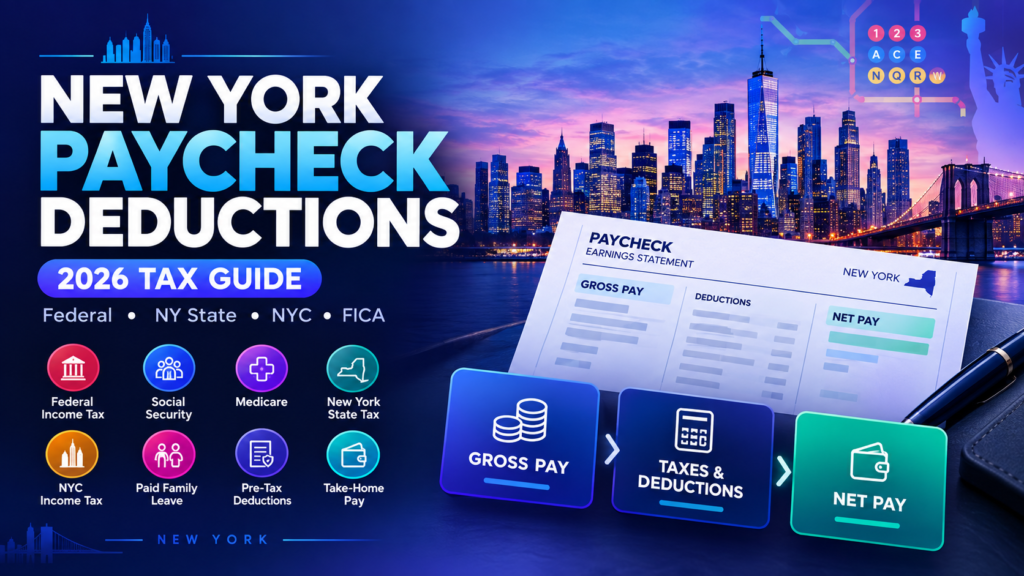
Your New York Paycheck, From Gross to Net
The easiest way to understand your paycheck is to look at it as a series of steps:
1. Gross Pay
Salary + overtime + bonuses + other earnings
↓
2. Applicable Pre-Tax Deductions
Certain eligible retirement, benefit, or spending-account contributions
↓
3. Federal Taxes
Federal income tax + Social Security + Medicare
↓
4. New York Taxes
New York State tax + NYC or Yonkers tax, when applicable
↓
5. Other Payroll Deductions
Insurance + retirement + other deductions
↓
Net Pay
The amount that actually reaches your bank account
This is why your salary and take-home pay can be very different.
Why Two People With the Same Salary Can Have Different Paychecks
Let’s say two employees both earn:
$80,000 per year
Employee A:
- Single
- Lives outside NYC
- No retirement contribution
- Different benefit elections
Employee B:
- Single
- Lives in NYC
- Contributes to a 401(k)
- Has employee-paid health insurance
They have the same annual salary.
But they can have different take-home pay.
Why?
Because paycheck deductions depend on more than salary.
Your:
- Location
- Filing status
- W-4 information
- NY withholding information
- Retirement contributions
- Insurance costs
- Pay frequency
- Other deductions
can all affect the amount deposited into your bank account.
Why Did My Paycheck Change?
Your salary may remain the same while your paycheck changes.
Here are some common reasons.
Your W-4 Changed
Changing federal withholding information can change federal income-tax withholding.
Your New York Withholding Information Changed
Changes to your New York withholding information can affect state withholding.
Your Benefits Changed
A change in health insurance or another employee benefit can affect your paycheck.
Your 401(k) Contribution Changed
Increasing your retirement contribution can reduce your take-home pay.
You Received Overtime or a Bonus
A paycheck containing supplemental wages can look different from your normal paycheck.
You Reached the Social Security Wage Base
For 2026, Social Security applies up to the $184,500 wage base. Once you reach that limit, Social Security withholding generally stops for the rest of that calendar year.
Pre-Tax vs. Post-Tax Deductions
This distinction is extremely important when calculating take-home pay.
What Is a Pre-Tax Deduction?
A qualifying pre-tax deduction can reduce the wages used for certain taxes.
Examples can include:
- Traditional 401(k)
- Certain health insurance premiums
- HSA contributions through payroll
- FSA contributions
But remember:
Pre-tax does not mean tax-free for every tax.
Different deductions can affect different tax calculations.
What Is a Post-Tax Deduction?
A post-tax deduction is generally taken after the applicable taxes have been calculated.
One common example is a Roth 401(k) contribution.
Other deductions may also be treated as post-tax depending on the specific benefit or payroll arrangement.
Always check the treatment of the specific deduction rather than assuming every payroll deduction works the same way.
How to Read Your New York Paystub
Your paystub may look complicated, but you can break it into a few important sections.
| Paystub Item | What It Usually Means |
|---|---|
| Gross Pay | Earnings before deductions |
| Federal Income Tax | Federal income-tax withholding |
| Social Security | Social Security portion of FICA |
| Medicare | Medicare portion of FICA |
| NY State Tax | New York State income-tax withholding |
| NYC Tax | NYC resident income-tax withholding, when applicable |
| Yonkers Tax | Yonkers withholding, when applicable |
| PFL | Paid Family Leave contribution |
| 401(k) | Retirement contribution |
| Health Insurance | Employee benefit cost |
| Net Pay | Amount left after applicable deductions |
Your employer may use different abbreviations or labels.
A Simple New York Paycheck Formula
If you want to understand the basic calculation, use this framework:
Gross Pay
− Applicable Pre-Tax Deductions
= Taxable Wage Amounts for the Relevant Taxes
Then account for:
Federal Income Tax
- Social Security
- Medicare
- NY State Income Tax
- NYC or Yonkers Tax, if applicable
- Paid Family Leave, if applicable
- Other Payroll Deductions
=
Estimated Net Pay
The word estimated is important.
Actual payroll withholding uses official tax tables, formulas, withholding forms, and payroll methods. There is no single percentage that correctly calculates every New York paycheck.
New York publishes separate 2026 withholding tables for NY State, NYC, and Yonkers.
New York Paycheck Deductions at a Glance
| Deduction | Who May Have It? | 2026 Information |
|---|---|---|
| Federal Income Tax | Employees subject to federal withholding | Progressive federal rates |
| Social Security | Most covered employees | 6.2% up to $184,500 wage base |
| Medicare | Most covered employees | 1.45%, no wage cap |
| Additional Medicare | Higher earners | Additional 0.9% withholding can apply |
| NY State Income Tax | Employees subject to NY withholding | Progressive rates and withholding tables |
| NYC Income Tax | NYC residents | 3.078%–3.876% resident rates |
| Yonkers Tax | Applicable Yonkers taxpayers | Separate Yonkers withholding rules |
| Paid Family Leave | Covered NY employees | 0.432%, maximum $411.91 for 2026 |
Federal and New York figures above are based on the applicable 2026 official tax and withholding information.
Is Payroll Withholding the Same as Your Final Tax Bill?
No.
This is one of the most important things to understand.
Paycheck withholding ≠ final tax liability
Your employer withholds money throughout the year based on your withholding information and applicable payroll rules.
When you file your tax return, your actual tax liability is calculated using your full-year income, deductions, credits, and other applicable information.
Depending on your situation, you may:
- Receive a tax refund
- Owe additional tax
- End up close to the amount already withheld
So seeing taxes deducted from every paycheck does not guarantee that you will have no tax due when you file.
How Much of Your Salary Do You Actually Keep?
There is no universal answer.
Someone earning $60,000 can have a different take-home amount from another person earning $60,000.
Someone earning $100,000 can also have a very different paycheck depending on their:
- Filing status
- NYC residency
- Retirement contributions
- Insurance
- W-4
- NY withholding form
- Pay frequency
- Other deductions
That’s why looking only at the salary number isn’t enough.
Your paycheck tells the real story.
The Fastest Way to Estimate Your New York Take-Home Pay
Doing the calculation manually can help you understand your paycheck.
But if you simply want to know:
“How much will I actually take home?”
you don’t need to calculate every deduction by hand.
Use our New York Paycheck Calculator 2026.
Enter your:
- Salary or gross pay
- Pay frequency
- Filing status
- New York location
- Pre-tax deductions
Then review your estimated:
Gross Pay → Federal Tax → FICA → NY Tax → NYC Tax → Net Pay
Calculate Your New York Paycheck
Use our New York Paycheck Calculator 2026 to estimate your take-home pay.
👉 [ADD YOUR CALCULATOR LINK HERE]
Frequently Asked Questions
How much tax is deducted from a New York paycheck?
There is no single tax percentage for every New York employee. Your paycheck deductions depend on your income, filing status, location, withholding information, pay frequency, benefits, and other deductions.
Does New York have state income tax?
Yes. New York has a state personal income tax with progressive rates and specific withholding methods.
Does NYC have an additional income tax?
Yes. New York City residents can be subject to NYC personal income tax in addition to New York State income tax. The 2026 NYC resident rates range from 3.078% to 3.876%.
Do I pay NYC tax if I work in NYC but live outside the city?
Not automatically. Simply working in New York City does not by itself make you an NYC resident for personal income-tax purposes.
What is the Social Security tax rate in 2026?
The employee Social Security rate is 6.2%, and the 2026 Social Security wage base is $184,500.
What is the Medicare tax rate in 2026?
The regular employee Medicare rate is 1.45% and there is no wage-base limit for Medicare tax.
What is Additional Medicare Tax?
An additional 0.9% Medicare withholding can apply when wages paid by an employer exceed $200,000 during the calendar year. Your final liability can depend on your overall tax situation.
What is Paid Family Leave on my New York paycheck?
Paid Family Leave is a New York program that can be funded through an employee payroll contribution. For 2026, the employee contribution rate is 0.432% of gross wages per pay period, with a maximum annual contribution of $411.91.
Why is my paycheck lower than my salary divided by 12?
Because dividing your annual salary by 12 gives you approximate gross monthly pay. Taxes, retirement contributions, insurance, and other deductions can reduce the amount you actually receive.
Can two people with the same salary have different take-home pay?
Yes. Filing status, residency, withholding forms, retirement contributions, insurance, pay frequency, and other deductions can all affect take-home pay.
Is paycheck withholding my final tax?
No. Paycheck withholding is money withheld during the year. Your final tax liability is determined when you file your tax return.
Final Takeaway
Calculating a New York paycheck becomes much easier when you stop looking at your salary as one number.
Start with your gross pay.
Then identify the deductions that apply to you.
Separate pre-tax deductions, tax withholding, and post-tax deductions.
Finally, subtract the applicable amounts to estimate your net take-home pay.
For 2026, some of the key federal figures are a 6.2% Social Security employee rate with a $184,500 wage base, a 1.45% Medicare employee rate with no wage cap, and federal standard deductions of $16,100 for single filers, $32,200 for married couples filing jointly, and $24,150 for heads of household.
New York also has its own state withholding rules, while NYC and Yonkers have separate rules that can affect your paycheck.
If you want to skip the manual calculations, use our New York Paycheck Calculator 2026 to estimate your take-home pay based on your salary, pay schedule, filing status, location, and deductions.
Disclaimer: This article is for general educational purposes and provides estimated information. Payroll withholding can vary based on individual circumstances, employer payroll methods, withholding forms, benefits, deductions, and changes in tax law. It is not tax, legal, or financial advice. For advice about your specific tax situation, consult a qualified tax professional.
2 thoughts on “New York Paycheck Deductions: How Much Tax Is Deducted in NY in 2026”