Updated November 2026 · Tax figures checked against IRS and NY State sources · Single filer, NYC resident
So you got a $100,000 offer in New York City, or you’re just curious what that number really means once the taxes come out. Fair question, because the gap between $100,000 on paper and what lands in your bank account is bigger in NYC than almost anywhere else in the country.
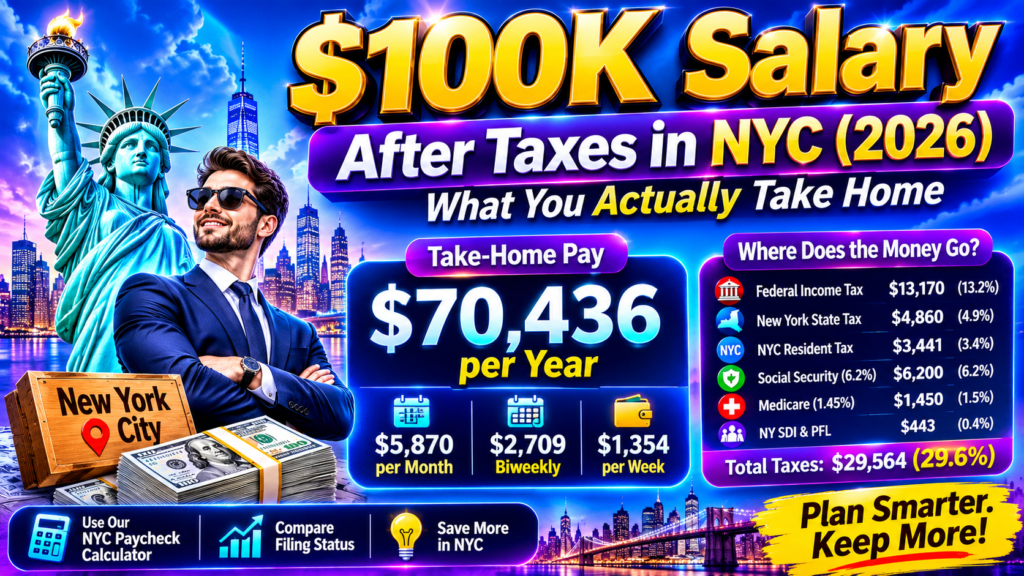
Here’s the short version: a single person living in NYC and earning $100,000 takes home about $70,436 a year in 2026. That works out to roughly $5,870 a month or $2,709 every two weeks. About 29.6% of your pay goes to taxes and payroll contributions.
Let’s walk through exactly where that money goes, why NYC takes more than most places, and what you can do about it.
Your $100,000 paycheck at a glance
These numbers assume you’re single, live in one of the five boroughs, take the standard deduction, and have no 401(k), HSA or FSA contributions. All figures use 2026 tax rules.
| Pay period | Gross pay | Estimated take-home |
|---|---|---|
| Yearly | $100,000.00 | $70,436 |
| Monthly | $8,333.33 | $5,869.67 |
| Semi-monthly (24 checks) | $4,166.67 | $2,934.83 |
| Biweekly (26 checks) | $3,846.15 | $2,709.08 |
| Weekly | $1,923.08 | $1,354.54 |
| Hourly (2,080 hours) | $48.08 | $33.86 |
Want your own numbers? Plug in your filing status and deductions in our NYC Paycheck Calculator.
Where the other $29,564 goes
Here’s the full breakdown of what comes out of a $100,000 salary, using the same assumptions as above.
| Where it goes | Per year | Per biweekly paycheck |
|---|---|---|
| Federal income tax | $13,170 | $506.54 |
| New York State income tax | $4,860 | $186.91 |
| NYC resident income tax | $3,441 | $132.35 |
| Social Security (6.2%) | $6,200 | $238.46 |
| Medicare (1.45%) | $1,450 | $55.77 |
| NY SDI and Paid Family Leave | $443 | $17.04 |
| Take-home pay | $70,436 | $2,709.08 |
If you add up the six deductions you get $29,564, which is where the 29.6% figure comes from.
Why NYC takes more than most places
Most Americans pay two layers of income tax: federal and state. If you live in New York City you pay three, and that third layer is the one that surprises people.
Federal income tax ($13,170). The 2026 standard deduction for a single filer is $16,100, so only $83,900 of your salary is actually taxed. The first $12,400 is taxed at 10%, the next chunk up to $50,400 at 12%, and the rest at 22%. That’s why you don’t pay 22% on the whole $100,000.
New York State income tax ($4,860). New York has its own brackets, which for your income range run from 3.9% up to 5.9%. After the $8,000 state standard deduction, you’re taxed on $92,000. Because you’re under $107,650 of income, you also avoid New York’s tax-benefit recapture, which quietly raises the effective rate for higher earners.
NYC resident income tax ($3,441). This is the one most people don’t see coming. If you live in the five boroughs, the city charges its own income tax, with rates between 3.078% and 3.876%. It only applies to residents. If you work in the city but live elsewhere, you don’t pay it. More on that below, and you can see every bracket in our guide to
NYC local income tax ratesSocial Security and Medicare ($7,650). These are the standard payroll taxes everyone pays, 6.2% for Social Security (up to a $184,500 wage cap, which you’re well under) and 1.45% for Medicare. Not sure why OASDI shows up on your stub? We explain it in
What Is OASDI Tax on a PaycheckNY SDI and Paid Family Leave ($443). SDI is capped at $31.20 a year and Paid Family Leave at $411.91. Some employers don’t collect SDI from employees, so you may see a slightly smaller number on your stub. Details are in our
Your average tax rate vs. what you pay on your next dollar
This is the part that actually helps when you’re negotiating a raise or deciding on overtime.
Your average (effective) rate is about 29.6%. That’s total taxes divided by total pay.
But your marginal rate, the tax on the next dollar you earn, is higher. At $100,000 in NYC, an extra dollar gets hit by 22% federal, 5.9% state, 3.876% city, plus 7.65% for Social Security and Medicare. That adds up to roughly 39.4 cents of every extra dollar.
So if you get a $5,000 raise, expect to keep around $3,000 of it, not the full $5,000. Nothing is wrong with your paycheck. That’s just how progressive brackets work.
Does filing status change the answer?
Yes, quite a bit. Here’s the same $100,000 salary for each filing status, assuming you live in NYC and this is the only income in the household (a married filer with no spouse wages).
| Filing status | Annual take-home | Per biweekly check | Total tax rate |
|---|---|---|---|
| Married Filing Jointly | $77,033 | $2,962.82 | 23.0% |
| Head of Household | $74,480 | $2,864.62 | 25.5% |
| Single | $70,436 | $2,709.08 | 29.6% |
If your spouse also earns income, the married numbers change, because the household is taxed on both salaries together. Use the spouse wages field in our calculator to see your real situation.
NYC resident vs. living elsewhere in New York
Here’s what the city tax costs a single filer at $100,000:
| Where you live | Annual take-home | Per biweekly check | NYC tax |
|---|---|---|---|
| NYC (five boroughs) | $70,436 | $2,709.08 | $3,441 |
| Elsewhere in New York State | $73,877 | $2,841.43 | $0 |
That’s $3,441 a year, or $132.35 per paycheck, just for the NYC address.
What if you live in New Jersey and work in NYC? You generally don’t pay NYC resident income tax, because that tax is based on where you live, not where you work. You may still owe New York State income tax on wages earned in New York. Try our NYC Commuter Tax Calculator to estimate it.
How a 401(k) changes your take-home
Traditional 401(k) contributions come out before income tax, so they shrink your tax bill. They don’t reduce Social Security or Medicare tax though, so the savings are smaller than the contribution.
Here’s a rough example. Say you put $10,000 into a traditional 401(k). At your tax rates, that cuts your income taxes by roughly $3,100 (about 22% federal, 5.4% to 5.9% state and 3.876% city). Your take-home drops by about $6,900, not the full $10,000, and you’ve put $10,000 toward retirement. The 2026 limit for most people is $24,500.
The exact result depends on your plan and benefits, so run your own numbers in the calculator using the 401(k) field. Health premiums, HSA and FSA contributions can lower your taxes too, and they also reduce FICA.
What does $100,000 feel like in New York?
It depends a lot on rent. Two quick rules of thumb:
- The 40x rule: Many NYC landlords want your annual income to be at least 40 times the monthly rent. At $100,000, that points to rent of about $2,500 a month, or lower if you have debt or no guarantor.
- The 50/30/20 split: A common budgeting guideline puts 50% of take-home pay toward needs, 30% toward wants and 20% toward savings. On $5,870 a month, that’s about $2,935 for needs, $1,761 for wants and $1,174 for savings.
In practice, NYC rent can push the “needs” slice above 50%, so you may have to trim wants or savings. If you want to see what salary your lifestyle needs, our NYC Salary Needed Calculator can help, and the NYC vs. other cities comparison shows how the same salary stacks up elsewhere.
How $100,000 compares to nearby salaries
Going from $75,000 to $100,000 adds $25,000 to your gross pay but only about $15,124 to your take-home. The same pattern holds as you climb, so roughly $14,000 to $15,000 of every extra $25,000 stays with you.
| Annual salary | Biweekly take-home | Annual take-home | Total tax rate |
|---|---|---|---|
| $75,000 | $2,127.39 | $55,312 | 26.3% |
| $100,000 | $2,709.08 | $70,436 | 29.6% |
| $125,000 | $3,281.48 | $85,318 | 31.7% |
| $150,000 | $3,833.76 | $99,678 | 33.5% |
Same assumptions as above: single filer, NYC resident, biweekly pay, standard deduction, no pre-tax deductions.
Why your real paycheck might look different
These are estimates, not payroll withholding. Your actual stub can differ because of:
- Your Form W-4 and New York Form IT-2104 settings
- Pre-tax benefits like health insurance, commuter benefits, HSA or FSA
- Bonuses, commissions or stock pay, which are often withheld differently from regular salary (see our bonus and RSU tax calculator)
- Tax credits, itemized deductions or other income
- Yonkers taxes, which these numbers don’t include
- Whether your employer collects NY SDI
If your paycheck looks way off, our guide on why your NYC paycheck is so low walks through the usual suspects.
The bottom line
A $100,000 salary leaves a single NYC resident with about $70,436 a year, or $2,709 every two weeks. The city tax alone costs $3,441, and each extra $1,000 you earn keeps only about $600. Filing status, a 401(k) and where you live can move your take-home by thousands of dollars, so run your own numbers in the NYC Paycheck Calculator before you accept an offer or sign a lease.
Frequently asked questions
How much is $100,000 a year after taxes in NYC? A single NYC resident takes home about $70,436 a year, which is around $5,870 a month, under 2026 tax rules and with no pre-tax deductions.
How much is $100,000 biweekly after taxes in NYC? About $2,709 per biweekly paycheck for a single filer. If you’re paid semi-monthly, it’s about $2,935 per check.
What percent of $100,000 goes to taxes in NYC? About 29.6% in total, counting federal, state and city income tax plus Social Security, Medicare, SDI and Paid Family Leave.
How much does NYC income tax cost on $100,000? About $3,441 a year for a single resident, or around $132 per biweekly paycheck. Only people who live in the five boroughs pay it.
Is $100,000 a good salary in NYC? It can be comfortable or tight depending on rent, debt and family size. After taxes you have roughly $5,870 a month, and many landlords would approve rent up to about $2,500 at that income.
Do I pay NYC tax if I work in the city but live in New Jersey? Generally no, because NYC resident tax is based on where you live. New York State tax may still apply to wages earned in New York.
Related calculators and guides
Related calculators and guides
Run your own numbers or dig into the details behind them.
Sources
Official 2026 tax sources
Every rate, limit and deduction in our calculators comes from these four government sources. Open any of them to check the numbers yourself.
- IRS Tax inflation adjustments for tax year 2026 Federal brackets, standard deduction and the 401(k) limit. Open IRS page
- NY State Department of Taxation and Finance Form IT-2105-I (2026) State and city tax rates, standard deductions and the recapture worksheets. Open PDF form
- NY Paid Family Leave 2026 contribution rate and maximum The employee rate and the yearly cap used for Paid Family Leave. Open PFL page
- Social Security Administration 2026 wage base of $184,500 The yearly earnings limit for Social Security tax. Open SSA page
This page is for information only and is not tax advice. Estimates use the assumptions stated above.
Publishing details (internal, delete before publishing)
- URL: /salaries/100000-salary-nyc/
- Main keyword: 100k after taxes nyc
- SEO title: $100,000 Salary After Taxes in NYC (2026): Take-Home Pay
- Meta description: A $100,000 salary in NYC takes home about $70,436 a year ($2,709 biweekly) in 2026. See the full tax breakdown, filing status and NYC vs. non-NYC comparison.
- Extra keywords to use naturally: 100k salary after taxes new york city; 100000 after tax nyc; $100k biweekly take home nyc; how much is 100k after taxes in nyc
- Before publishing: check that the internal links above open correctly (especially the $50,000 page and the “why is my paycheck so low” page, since menu and footer URLs on the site differ), and add a featured image with alt text such as “$100,000 salary after taxes in NYC 2026”.