By the NYC Paycheck Calculators Editorial Team | Last updated: November 2, 2026 | IRS guidance referenced: Fact Sheet FS-2026-13 (August 6, 2026)
Quick Answer: Is Overtime Tax-Free in 2026?
The federal No Tax on Overtime provision does not make your entire overtime paycheck tax-free. Instead, eligible workers may claim a federal income tax deduction for qualified overtime compensation received during the year.
For most employees paid time-and-a-half, the qualifying amount is generally the additional half-time premium—not the full overtime payment.
For tax year 2026:
- Eligible taxpayers may deduct up to $12,500 of qualified overtime compensation.
- Married taxpayers filing jointly may deduct up to $25,000 combined.
- The deduction begins to phase out when modified adjusted gross income (MAGI) exceeds $150,000, or $300,000 for joint filers.
- For 2026, employers generally report qualified overtime on Form W-2, Box 12, Code TT.
- Social Security and Medicare taxes generally still apply to overtime pay.
- New York State and NYC income taxes are not automatically eliminated by the federal deduction.
The deduction is available for tax years 2025 through 2028 under Section 225 of the Internal Revenue Code.
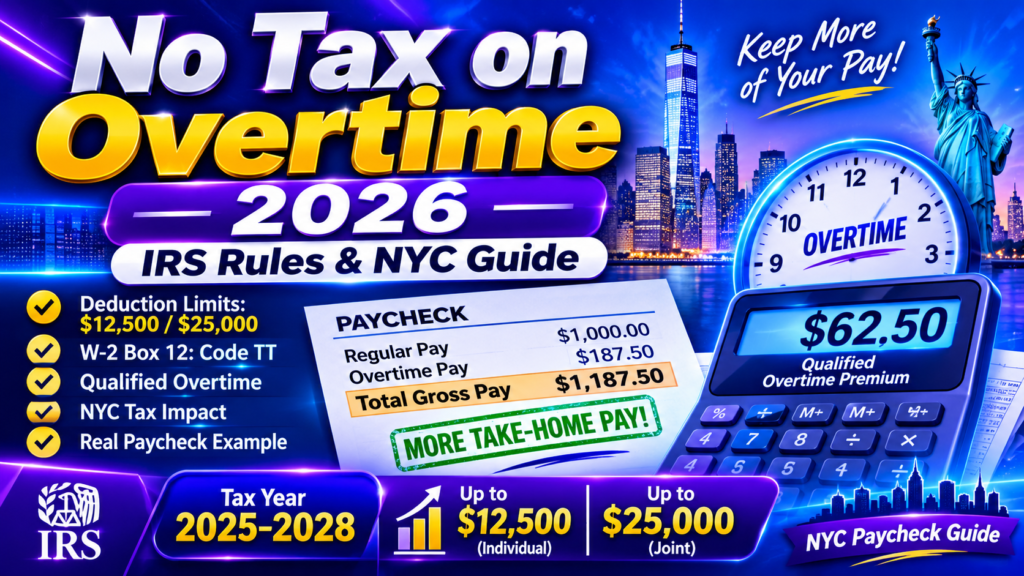
Table of Contents
- What Is the No Tax on Overtime Rule?
- 2026 Deduction Limits and Income Phase-Out
- Who Qualifies for the Deduction?
- What Overtime Pay Counts?
- How to Calculate Your Qualified Overtime
- Realistic Tax Savings Example
- What Is W-2 Box 12 Code TT?
- Federal Income Tax vs. FICA Taxes
- Does No Tax on Overtime Apply in New York and NYC?
- NYC Paycheck Example
- How to Claim the Deduction
- Can You Change Your Tax Withholding?
- What About Your 2025 Tax Return?
- Common Mistakes to Avoid
- Frequently Asked Questions
- Official Sources
What Is the No Tax on Overtime Rule?
The No Tax on Overtime provision was introduced through the One Big Beautiful Bill Act, signed into law on July 4, 2025.
The law added Section 225 to the Internal Revenue Code. It allows eligible individuals to deduct qualified overtime compensation from federal taxable income.
This is an income tax deduction—not an exemption from reporting wages.
Your employer generally still reports overtime as wages, and the overtime pay remains subject to applicable payroll taxes. The deduction is applied when calculating your federal income tax liability.
For employees who receive the standard time-and-a-half overtime rate, the qualifying amount is generally the additional half of their regular hourly rate.
Example:
If your regular hourly rate is $25, your overtime rate is $37.50.
- Regular hourly pay: $25.00
- Overtime hourly pay: $37.50
- Additional overtime premium: $12.50
The $12.50 premium is generally the qualified overtime amount for each eligible overtime hour—not the entire $37.50.
The deduction is temporary under current law and applies to tax years 2025, 2026, 2027, and 2028.
2026 Deduction Limits and Income Phase-Out
The maximum deduction depends on your filing situation and modified adjusted gross income.
| Tax situation | Maximum deduction |
|---|---|
| Eligible individual return | $12,500 |
| Married Filing Jointly | $25,000 combined |
| Married Filing Separately | Not eligible |
The deduction starts decreasing when MAGI exceeds the applicable income threshold.
| Filing situation | MAGI threshold |
|---|---|
| Individual taxpayer | $150,000 |
| Married Filing Jointly | $300,000 |
For every $1,000—or fraction of $1,000—that MAGI exceeds the threshold, the deduction is reduced by $100.
Phase-Out Examples
Example 1: Individual with $155,500 MAGI
- Starting deduction limit: $12,500
- MAGI above threshold: $5,500
- Phase-out units: 6
- Reduction: 6 × $100 = $600
- Remaining maximum deduction: $11,900
Example 2: Married Filing Jointly with $305,500 MAGI
- Starting deduction limit: $25,000
- MAGI above threshold: $5,500
- Phase-out units: 6
- Reduction: 6 × $100 = $600
- Remaining maximum deduction: $24,400
These are maximum amounts after the income phase-out. Your actual deduction cannot exceed the qualified overtime compensation you received and properly reported.
MAGI for this provision generally starts with adjusted gross income and adds back certain foreign-income exclusions under Sections 911, 931, and 933.
Who Qualifies for the Deduction?
You may qualify if you meet the requirements under Section 225 and applicable IRS guidance.
Generally, you must:
- Receive qualified overtime compensation required under the Fair Labor Standards Act (FLSA).
- Have the qualifying overtime properly reported on the required information statement.
- Have a Social Security number valid for employment, issued by the Social Security Administration before the due date of your return, including extensions.
- Follow the applicable filing-status rules.
- Stay within the deduction limits and income phase-out rules.
Which Filing Statuses Are Eligible?
Eligible filing situations can include:
- Single
- Head of Household
- Qualifying Surviving Spouse
- Married Filing Jointly
Important: If you are married under the applicable tax rules, you and your spouse must file a joint federal return to claim this deduction. Married Filing Separately does not qualify.
If both spouses receive qualified overtime, each person’s qualifying amount must meet the applicable reporting and eligibility requirements.
What Overtime Pay Counts?
Not every payment described by an employer as overtime automatically qualifies.
The deduction applies to overtime compensation required under Section 7 of the Fair Labor Standards Act.
For a typical nonexempt employee covered by the FLSA, overtime is generally required after 40 hours worked in a workweek.
What Usually Qualifies?
For a worker receiving the standard time-and-a-half rate:
- Regular rate: $25 per hour
- Required overtime rate: $37.50 per hour
- Qualified premium: $12.50 per overtime hour
What May Not Qualify?
Payments may not qualify when they are not required under the FLSA, even if an employer calls them overtime.
Examples can include:
- Extra pay for working weekends when FLSA overtime is not required.
- Holiday premiums that are not required under the FLSA.
- Extra payments under a company policy that exceed the amount required by federal overtime law.
- Overtime paid to an employee who is not covered by or eligible for FLSA overtime.
Special rules can apply to certain employees and alternative overtime arrangements. The actual FLSA requirements—not just the label on a paystub—determine the qualifying amount.
For more information, see the U.S. Department of Labor overtime guidance.
How to Calculate Your Qualified Overtime
For a typical employee paid time-and-a-half under the FLSA, the basic calculation is:
Qualified overtime premium = Overtime hours × Regular hourly rate × 0.5
Example: $25 Per Hour and 5 Overtime Hours
Suppose you earn $25 per hour and work 45 hours in one workweek.
| Pay calculation | Amount |
|---|---|
| Regular hours | 40 |
| Overtime hours | 5 |
| Regular hourly rate | $25.00 |
| Overtime hourly rate | $37.50 |
| Regular weekly pay | $1,000.00 |
| Total overtime pay | $187.50 |
| Total weekly gross pay | $1,187.50 |
| Qualified overtime premium | $62.50 |
The qualifying premium is calculated as:
5 × $25 × 0.5 = $62.50
The full $187.50 overtime payment is not the qualified deduction amount. Only the qualifying premium is generally considered.
Realistic Tax Savings Example
A deduction does not reduce your tax bill dollar-for-dollar. It reduces the income on which your federal income tax is calculated.
Consider this example:
- Hourly rate: $25
- Overtime hours: 5 per week
- Weeks worked: 52
- Qualified overtime premium per week: $62.50
Annual qualified overtime:
$62.50 × 52 = $3,250
Assume the taxpayer is single, has no other income or adjustments, takes the 2026 standard deduction of $16,100, and the entire deduction reduces income otherwise taxed at a 12% marginal federal rate.
| Calculation | Amount |
|---|---|
| Annual gross wages | $61,750 |
| 2026 standard deduction | $16,100 |
| Approximate taxable income before overtime deduction | $45,650 |
| Qualified overtime deduction | $3,250 |
| Illustrative marginal federal rate | 12% |
| Estimated federal income tax reduction | $390 |
Illustrative federal income tax reduction: approximately $390.
This is an example, not a guaranteed refund or tax saving for every worker. Your actual result depends on your complete tax return, income, filing status, other deductions, credits, and applicable tax rates.
The deduction also does not mean your employer stops withholding federal income tax from overtime wages.
What Is W-2 Box 12 Code TT?
For tax year 2026, employers generally must separately report qualified overtime compensation on Form W-2, Box 12, using Code TT.
This reporting information helps eligible employees determine the amount they may claim, subject to the applicable deduction limits and income phase-out.
What Does Code TT Show?
Code TT reports qualified overtime compensation paid during the year. It generally reflects the qualifying premium above the regular rate—not the entire overtime payment.
For example:
- Qualified overtime reported: $4,000
- W-2 Box 12 Code TT: $4,000
- Potential deduction before other limits: $4,000
The final deductible amount may be lower because of the annual cap and income phase-out.
What If Your W-2 Code TT Is Missing or Incorrect?
For 2026, the IRS reporting rules are important:
- You generally cannot use an amount greater than the qualified overtime compensation reported on your properly furnished W-2, Box 12, Code TT.
- If your employer omitted or understated the amount, request a corrected Form W-2c.
- If your employer furnishes a corrected W-2c, you may use the corrected qualifying amount.
- If Code TT is overstated, you may claim only the actual qualified overtime compensation paid—not the inflated amount.
- Form 4852 cannot be used to create a missing Code TT amount for this deduction.
The special reporting relief that applied to tax year 2025 does not continue into 2026.
Federal Income Tax vs. FICA Taxes
The overtime deduction does not remove overtime wages from every tax.
| Tax type | Does the overtime deduction eliminate it? |
|---|---|
| Federal income tax | May reduce taxable income |
| Social Security tax | No |
| Medicare tax | No |
| New York State income tax | Not automatically |
| NYC resident income tax | Not automatically |
Social Security and Medicare
Employee FICA taxes generally continue to apply to overtime wages.
For 2026, the standard employee rates are:
- Social Security: 6.2%, subject to the annual wage base.
- Medicare: 1.45%.
- Combined standard employee FICA rate: 7.65%.
Additional Medicare Tax may also apply to higher-wage taxpayers when the applicable threshold is reached.
Does No Tax on Overtime Apply in New York and NYC?
This is especially important for workers who live or work in New York City.
The federal deduction does not automatically create a matching New York State or NYC income tax deduction.
New York’s resident income tax calculation begins with federal adjusted gross income and then applies New York additions and subtractions.
The federal qualified overtime deduction is claimed after federal AGI when calculating federal taxable income. It therefore does not automatically reduce the federal AGI starting point used in the New York calculation.
What About New York Assembly Bill A8965A?
New York Assembly Bill A8965A proposed a state subtraction for overtime compensation.
As of November 2, 2026, the bill’s listed status is In Assembly Committee. Its action history shows that it was held for consideration in Ways and Means on June 4, 2026.
A proposed bill is not the same as enacted tax law.
Until New York enacts an applicable provision, workers should not assume that the federal overtime deduction also reduces their New York State or NYC income tax.
Check the New York Senate bill status before filing because legislative status can change.
Do NYC Residents Still Pay NYC Income Tax on Overtime?
Generally, yes. NYC residents remain subject to applicable NYC resident income tax rules. The federal overtime deduction does not automatically remove overtime wages from NYC tax calculations.
A person who works in NYC but lives outside the city generally does not owe NYC resident income tax simply because the job is located in NYC. Other New York State and local tax rules may still apply.
NYC Paycheck Example
Let’s look at a practical weekly paycheck example for an NYC worker.
Assumptions:
- Regular hourly rate: $25
- Regular hours: 40
- Overtime hours: 5
- Overtime rate: $37.50
- Total weekly hours: 45
- Standard employee FICA rates apply
| Paycheck item | Weekly amount |
|---|---|
| Regular pay | $1,000.00 |
| Overtime gross pay | $187.50 |
| Total gross pay | $1,187.50 |
| Qualified overtime premium | $62.50 |
| Social Security (6.2%) | $73.63 |
| Medicare (1.45%) | $17.22 |
| Combined employee FICA | $90.84 |
| Federal income tax withholding | Depends on Form W-4 |
| NY State withholding | Depends on Form IT-2104 |
| NYC withholding | Depends on residency and withholding details |
The qualified overtime premium is $62.50 for this week. If the same schedule continues for 52 weeks, the annual qualified premium would be $3,250.
This table is not a complete take-home-pay calculation. Federal, New York State, and NYC withholding depend on filing status, W-4 entries, IT-2104 information, pay frequency, pre-tax benefits, other income, and other circumstances.
Use our NYC Paycheck Calculator to estimate your paycheck after applicable taxes and deductions.
How to Claim the Deduction
For tax year 2026, eligible taxpayers should use the IRS form and instructions designated for claiming the qualified overtime deduction on their 2026 federal return. Check the latest IRS instructions when the 2026 filing forms become available.
Before filing:
- Collect your Form W-2 and review Box 12, Code TT.
- Confirm that the reported amount represents qualified overtime under the FLSA.
- Check your filing status and Social Security number eligibility.
- Calculate your MAGI and applicable income phase-out.
- Apply the annual deduction limit.
- Complete the qualified overtime section of the applicable IRS form.
- Transfer the resulting deduction to the appropriate part of your federal return.
Do not enter the entire overtime amount as a deduction. Use the qualifying amount and follow the final IRS form instructions for tax year 2026.
Can You Change Your Tax Withholding?
You may be able to adjust your federal income tax withholding if you expect to qualify for the overtime deduction.
The IRS provides Form W-4 and a Tax Withholding Estimator to help employees review their federal withholding.
You can use the IRS Tax Withholding Estimator to review your situation.
For New York State and NYC withholding, Form IT-2104 is the employee’s withholding allowance certificate. It is given to your employer and provides information used to calculate applicable New York State, NYC, and Yonkers withholding.
See the official 2026 Form IT-2104 instructions.
Changing withholding does not change the amount of tax you ultimately owe. Review your complete tax situation before changing payroll elections.
What About Your 2025 Tax Return?
The reporting rules for 2025 were different from the 2026 rules.
Employers were not required to separately report qualified overtime on a 2025 Form W-2 using Code TT. The IRS issued Notice 2025-69 to explain how eligible taxpayers could determine their 2025 deduction using available payroll records and applicable guidance.
If you filed your 2025 federal return and believe you missed an eligible deduction, you may be able to correct your return using Form 1040-X, subject to the applicable amendment and refund deadlines.
Review:
Do not use the 2025 reporting exception as a substitute for the 2026 Code TT requirement.
Common Mistakes to Avoid
Keep these points in mind when calculating your deduction:
- Deducting all overtime pay: Usually only the qualifying premium above the regular rate counts.
- Ignoring Code TT: For 2026, the properly reported amount is essential to the employee’s deduction.
- Assuming FICA disappears: Social Security and Medicare taxes generally still apply.
- Ignoring the income phase-out: The deduction can decrease when MAGI exceeds the threshold.
- Assuming New York follows federal law automatically: New York State and NYC treatment must be checked separately.
- Using the wrong filing status: Married taxpayers must file jointly to claim this deduction.
Frequently Asked Questions
1. Is overtime completely tax-free in 2026?
No. Eligible workers may deduct qualified overtime compensation from federal taxable income, subject to the law’s limits. Overtime wages generally remain subject to payroll taxes.
2. How much overtime can I deduct in 2026?
The maximum is $12,500 for an eligible individual return and $25,000 for a joint return. Income phase-outs may reduce these limits.
3. Does the deduction apply to the full overtime payment?
Generally, no. For standard time-and-a-half overtime, the qualifying amount is usually the additional half-time premium.
4. Can married taxpayers filing separately claim it?
No. Married taxpayers must file a joint return to claim the deduction.
5. What is W-2 Code TT?
Code TT appears in Box 12 of the 2026 Form W-2 and reports qualified overtime compensation paid during the year.
6. Do Social Security and Medicare taxes still apply?
Yes. Qualified overtime compensation generally remains subject to employee Social Security and Medicare taxes.
7. Does the deduction reduce NYC income tax?
Not automatically. The federal deduction does not by itself create a New York State or NYC deduction.
8. What if my employer leaves Code TT off my W-2?
Ask your employer for a corrected Form W-2c. For 2026, you generally cannot use an omitted amount unless it is properly corrected and reported.
9. Is the deduction permanent?
No. Under current law, it applies to tax years 2025 through 2028.
10. Can I claim the deduction if I take the standard deduction?
Yes. The overtime deduction is available whether you itemize or take the standard deduction, provided you meet the eligibility requirements.
Official Sources
For accurate and updated information, use these primary government and statutory sources:
- IRS Fact Sheet FS-2026-13: Updated Qualified Overtime FAQs (PDF)
- IRS Questions and Answers About the New Deduction for Qualified Overtime Compensation
- 26 U.S. Code § 225: Qualified Overtime Compensation
- IRS Instructions for Forms W-2 and W-3
- IRS Notice 2025-69 (PDF)
- U.S. Department of Labor: Overtime Pay
- New York Form IT-201 Instructions
- New York Form IT-2104 Instructions
- New York Assembly Bill A8965A
- IRS Tax Withholding Estimator
- IRS Form 1040-X Instructions
This article provides general educational information and is not individualized tax, legal, or accounting advice. Tax rules and administrative guidance can change. Consult a qualified tax professional about your circumstances and review the latest IRS and New York instructions before filing.